
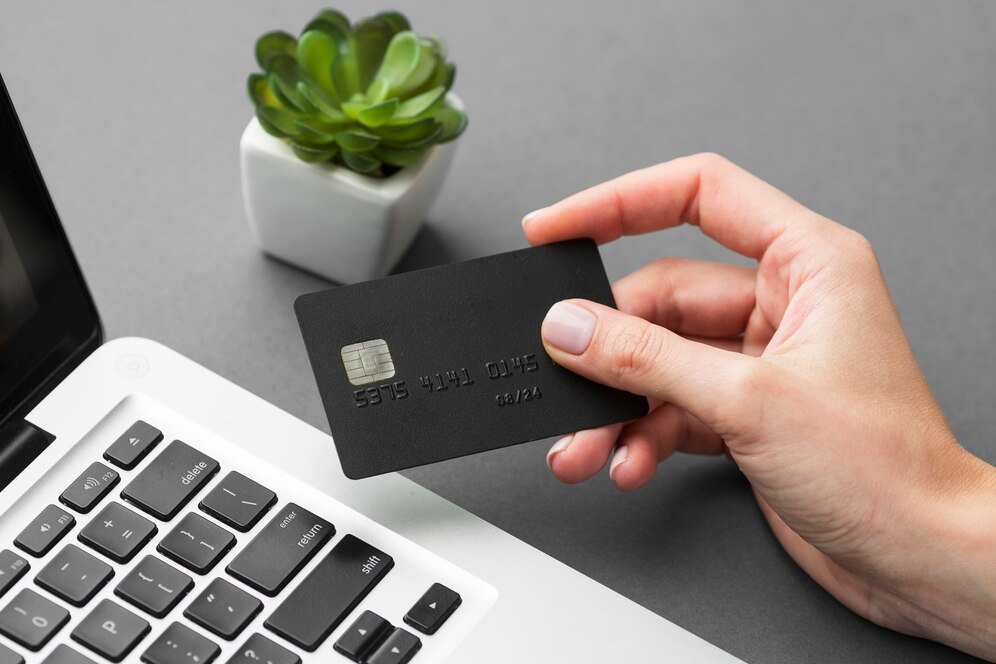
Putting business expenses on your personal credit card seems like the natural thing to do when your business is just starting out. Odds are you already have a personal credit card or two with great terms, high credit limits, cash-back programs, or other perks, so why would you start from scratch with a new card?
But things can quickly get messy if you choose that path. Accounting gets confusing, costing you more time than you probably have to give. And blurry financial lines can really become problematic at tax time, leading to filing delays or worse.
Even if you can stay on top of your spending and keep expenses properly categorized, relying on a personal card robs you of the opportunity to build credit for your company. Opting for a business credit card allows you to build a business credit history, which helps to secure loans and lines of credit as the company grows.
“Having a reliable and efficient payment process is essential in today’s fast-paced business world,” says Swapnil Shinde, co-founder and CEO of Zeni. “Companies need a solution that integrates seamlessly with financial systems, streamlines the review process of expenses, and simplifies expense management. Business credit cards provide all of that and more.”
Zeni combines AI-powered bookkeeping with a team of financial experts to provide sole proprietors and other businesses with a one-stop solution for managing finances accurately, efficiently, and in real time. It’s the future of business finance, giving fast-growing startups the insights they need to power high-velocity decision-making.
“Separating your personal and business finances is one of the best advice I can give new entrepreneurs,” says Shinde. “Even if you are still a company of one, you’ll benefit from having a business credit card. It makes tracking expenses so much easier, which means your books are better organized. It also makes it easier to manage cash flow, which is critical in the early phases of your business launch.”
Approving investor appeal with business credit cards
While credit cards are typically considered a financial tool, they can also be a reputational tool for companies looking to attract investors. When finances are messy, investors tend to take a pass. Business credit cards make it much easier to present buttoned-up books.
“Using a business credit card to keep your finances in line increases your credibility when pitching to investors,” Shinde says. “It gives you what you need to have clean and organized financial records. That shows you are focused on being financially responsible, which investors like to see.”
Improving cash flow with business credit cards
All businesses must optimize their cash flow to thrive. Business credit cards can help in that area by providing short-term financing to cover immediate expenses when cash flow is tight.
“Credit card purchases don’t need to be paid off immediately,” Shinde says, “which means they give businesses some financial flexibility that can really help to manage seasonal variations or unexpected expenses.”
On the flip side, the easy credit business cards extend can cause business problems if not properly managed. They typically charge high interest rates, with 14 percent being considered reasonable, and make it easy for employees to overspend by doing away with the need for purchase approvals.
“Without tight oversight or automated spending limits, business cards lead to unnecessary or unauthorized employee purchases, which can trigger cash flow problems,” Shinde warns. “And companies that don’t pay off credit balances each month will find the high interest rates can quickly add up and cut into their bottom line. If you are a startup operating on tight financial margin, overspending on credit cards can sink you.”
Securing the best benefits of business credit cards
Just like personal credit cards, some business cards are better than others. Maximizing the value of cards requires knowing what features will pay the highest dividends. For example, choosing cards with no transactional or annual fees cuts down on your financial management costs.
“Many credit cards have hidden fees that can get pricey,” Shinde points out. “Look for the cards with no annual fees, foreign transaction fees, or hidden costs that could eat into your business profits.”
Cards that require personal guarantees should be avoided at all costs. A personal guarantee puts your personal finances at risk if your business finances go south.
“Committing to a card with a personal guarantee means you may ultimately need to pay off your business expenses out of your own pocket,” Shinde explains. “Avoiding personal guarantees means the debt you might incur through your business will stay with your business and not threaten your personal assets like your house or vehicle.”
AI integration is an emerging feature that can boost the potential of a business credit card. Card systems that leverage the power of AI can automatically categorize transactions, identify vendors, and assign classes to expenses, all of which make for a faster month-end close.
With business finances, even slight advantages can give companies the margin they need to move ahead and make the most of opportunities. Business credit cards, when used in the right way, provide those small advantages and open doors to smarter financial management.




Be First to Comment